The question raised by the annual tables
Shishu annual reported accounts fell 37.65% from FY 2024-25 to FY 2025-26, and disbursement fell 34.04%, for loans up to Rs 50,000. Official evidence records graduation to larger loans. Explaining this decline requires figures following the same borrowers into their subsequent borrowing, including formal credit outside MUDRA.
Where did the previous year's Shishu borrowers go? The Government should provide linked borrower figures showing who retained Shishu, moved to Kishor, Tarun or Tarun Plus, obtained other formal credit, or had no observed subsequent loan. It should identify any existing publication that supplies these figures.
Source: MUDRA PMMY Overall Performance, financial year 2024-25, Financial year 2024-25 . MUDRA PMMY Overall Performance, financial year 2025-26, Financial year 2025-26 . Lok Sabha Starred Question 198, 2024-12-09 . Lok Sabha Unstarred Question 2466, 2026-08-03 . KPMG Impact Assessment of PMMY, NITI-sponsored, November 2023 .
Annual MUDRA changes
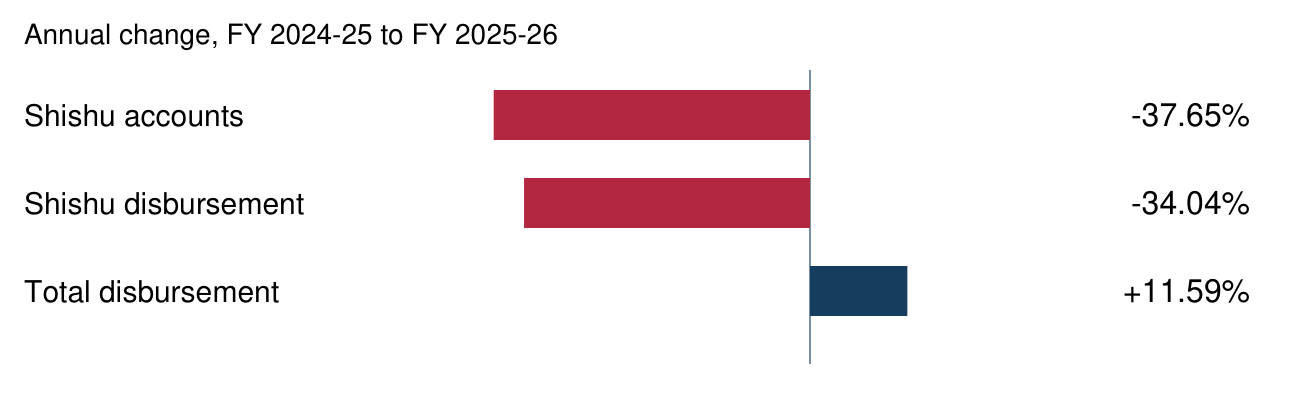
Read the chart values
| Category | Per cent |
|---|---|
| Shishu accounts | -37.65% |
| Shishu disbursement | -34.04% |
| Total disbursement | +11.59% |
MUDRA's annual table also records Shishu disbursement falling 34.04%, from Rs 103,424.68 crore in FY 2024-25 to Rs 68,216.54 crore in FY 2025-26. Both the reported account count and the money disbursed fell within this entry-level band over the same financial years.
MUDRA labels the annual count No Of A/Cs. That label does not establish how many distinct people borrowed, how many were first-time borrowers, or how the same borrowers moved between loan bands. The account decline alone cannot establish rejections or explain its cause.
Official evidence documents a pathway from Shishu to larger loans as businesses grow. Its contribution to the FY 2024-25 to FY 2025-26 decline needs to be measured. Linked borrower figures should show how many followed that pathway, how many obtained other formal credit, and how many had no observed subsequent loan.
Source: MUDRA PMMY Overall Performance, financial year 2024-25, Financial year 2024-25 . MUDRA PMMY Overall Performance, financial year 2025-26, Financial year 2025-26 .
Source: Lok Sabha Starred Question 198, 2024-12-09 . Lok Sabha Unstarred Question 2466, 2026-08-03 . KPMG Impact Assessment of PMMY, NITI-sponsored, November 2023 .
Entity exposure bands
Read the chart values
| Category | Per cent |
|---|---|
| Up to Rs 2 lakh | -13.00% |
| Rs 2 lakh to Rs 10 lakh | +5.00% |
| Rs 10 lakh to Rs 2 crore | +12.00% |
| Rs 2 crore to Rs 20 crore | +16.00% |
| Rs 20 crore to Rs 100 crore | +15.00% |
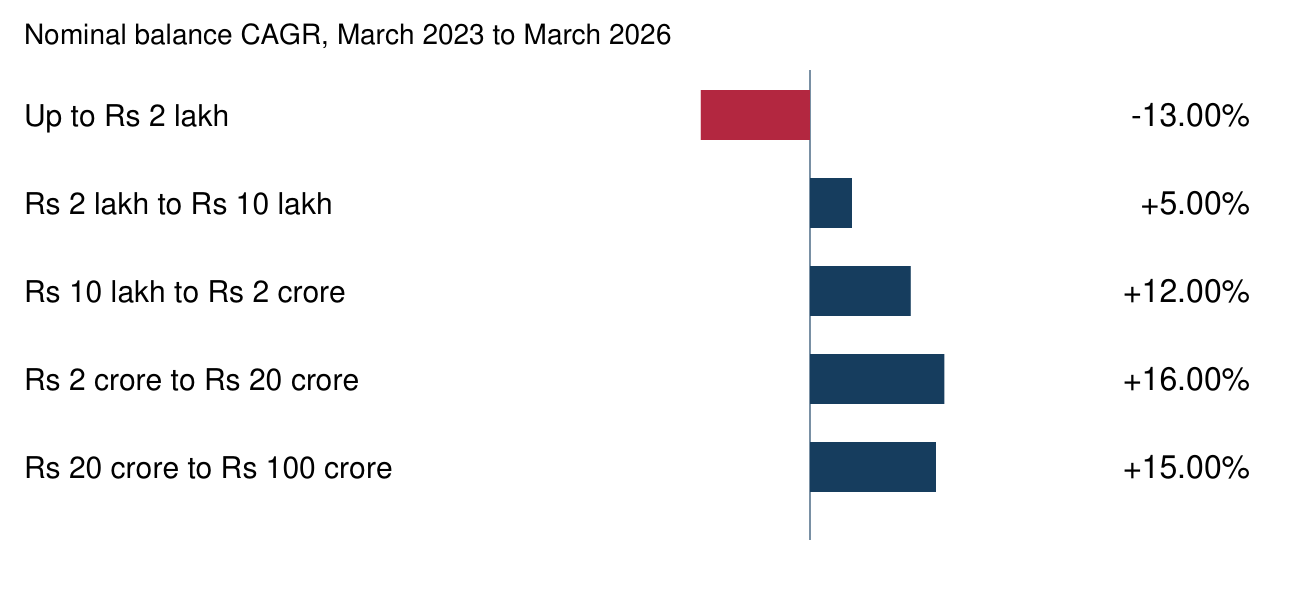
CIBIL-SIDBI's July 2026 report gives nominal outstanding-balance compound annual growth rate (CAGR) for March 2023 to March 2026 by entities' aggregate exposure: up to Rs 2 lakh, -13%; Rs 2-10 lakh, 5%; Rs 10 lakh-2 crore, 12%; Rs 2-20 crore, 16%; Rs 20-100 crore, 15%. Individual business-purpose borrowing grew 22% on its separate measure.
The CIBIL-SIDBI exposure bands group entities by aggregate borrowing exposure. They do not describe single-loan sizes or statutory MSME classes, and they do not track a fixed cohort. The up-to-Rs 2 lakh band holds only 0.1% of portfolio balance at March 2026; movement between bands may affect its measured growth. The March 2026 data are provisional.
Source: TransUnion CIBIL-SIDBI MSME Pulse, July 2026, 2026-07 .
Reported accounts and disbursement by category
| Category | FY 2024-25 | FY 2025-26 | Change |
|---|---|---|---|
| Shishu | 27,741,792 | 17,297,817 | -37.65% |
| Kishor | 24,969,887 | 30,431,772 | +21.87% |
| Tarun | 1,919,542 | 2,197,883 | +14.50% |
| Tarun Plus | 30,427 | 99,077 | +225.62% |
| Total | 54,661,648 | 50,026,549 | -8.48% |
| Category | FY 2024-25 | FY 2025-26 | Change |
|---|---|---|---|
| Shishu | 103,424.68 | 68,216.54 | -34.04% |
| Kishor | 279,571.54 | 347,611.49 | +24.34% |
| Tarun | 154,633.24 | 174,423.04 | +12.80% |
| Tarun Plus | 4,173.13 | 14,366.66 | +244.27% |
| Total | 541,802.58 | 604,617.73 | +11.59% |
Source: MUDRA PMMY Overall Performance, financial year 2024-25, Financial year 2024-25 . MUDRA PMMY Overall Performance, financial year 2025-26, Financial year 2025-26 .
Graduation and the borrower figures needed
The Finance Minister's Lok Sabha reply of 9 December 2024 describes borrowers moving from Shishu to Kishor and Tarun over the years. The Finance Ministry's reply of 3 August 2026 cites a November 2023 NITI-sponsored KPMG assessment reporting graduation among first-time entrepreneurs. Both establish documented evidence that must inform the explanation sought.
The November 2023 NITI-sponsored KPMG assessment describes lender practice after timely repayment and movement outside PMMY as borrowing needs increase. Its method was qualitative lender interviews, without a beneficiary survey. That older study cannot quantify linked borrower transitions from FY 2024-25 to FY 2025-26.
Source: Lok Sabha Starred Question 198, 2024-12-09 . Lok Sabha Unstarred Question 2466, 2026-08-03 . KPMG Impact Assessment of PMMY, NITI-sponsored, November 2023 .
| Category | Lakh accounts |
|---|---|
| Shishu | -104.44 |
| Kishor, Tarun and Tarun Plus combined | +58.09 |
| Total MUDRA | -46.35 |
The increase shown for the larger bands is the difference between their annual reported account totals. It neither measures gross borrower graduation nor sets an upper bound on it. Annual reported accounts do not identify distinct people or follow their borrowing histories. A borrower moving outside PMMY may still receive formal credit through another scheme or lender.
Source: MUDRA PMMY Overall Performance, financial year 2024-25, Financial year 2024-25 . MUDRA PMMY Overall Performance, financial year 2025-26, Financial year 2025-26 . KPMG Impact Assessment of PMMY, NITI-sponsored, November 2023 .
No quantified table linking Shishu borrowers from FY 2024-25 to FY 2025-26 was located in the specific official materials checked. The Government should identify publications supplying those figures and explain the annual decline through linked borrower movements, with a stated follow-up window and rules for removing duplicates and handling overlaps.
| Follow-up requested | What the figures should distinguish |
|---|---|
| Further Shishu borrowing | Follow prior-year borrowers into later Shishu loans. |
| Larger PMMY categories | Identify movement to Kishor, Tarun or Tarun Plus. |
| Other formal credit | Identify borrowing outside PMMY. |
| No observed subsequent loan | State the follow-up window and observation limits. |
| New entrants and repeat loans | Separate them from movement of earlier borrowers. |
| Duplicates and overlapping paths | Define how borrowers and multiple loans are counted. |
Source: MUDRA PMMY Overall Performance, financial year 2024-25, Financial year 2024-25 . MUDRA PMMY Overall Performance, financial year 2025-26, Financial year 2025-26 . Lok Sabha Starred Question 198, 2024-12-09 . Lok Sabha Unstarred Question 2466, 2026-08-03 . KPMG Impact Assessment of PMMY, NITI-sponsored, November 2023 . Economic Survey 2025-26, Box III.4, 2026 .
Broader credit is growing
RBI's Weekly Statistical Supplement gives annual M3 growth of 16.0% and commercial-sector credit growth of 17.7% on the same date, 15 October 2026. Commercial-sector credit therefore grew faster on that comparison. These figures do not support a claim that overall credit lagged money growth.
Source: RBI Weekly Statistical Supplement, 23 October 2026, 2026-10-23 .
The 31 July 2026 selected-bank figures show industrial micro/small credit growth of 22.6%, priority MSE (micro and small enterprises) growth of 24.1%, and weaker-sections growth of 15.2%. RBI's August 2026 release reports agriculture at 17.2%, industry at 18.2%, services at 24.3%, and personal loans at 16.9%. These broader measures show positive growth.
Source: RBI Sectoral Deployment of Bank Credit, July 2026, 2026-08-31 . RBI Sectoral Deployment of Bank Credit, August 2026, 2026-09-30 .
Annual MUDRA disbursements, CIBIL-SIDBI outstanding balances over March 2023 to March 2026, and RBI's later money and credit figures cover different periods and populations. A year's lending is a flow; an outstanding balance is a stock. Their comparison does not establish that rising M3 caused the earlier Shishu decline.
Provide linked figures for prior-year Shishu borrowers retaining Shishu, moving to Kishor, Tarun or Tarun Plus, obtaining other formal credit, or having no observed subsequent loan. Separate new entrants, repeat loans, exits and reporting changes. Define the follow-up window, duplicate-removal and overlap rules, and identify existing publications supplying these figures.
Source: MUDRA PMMY Overall Performance, financial year 2024-25, Financial year 2024-25 . MUDRA PMMY Overall Performance, financial year 2025-26, Financial year 2025-26 . TransUnion CIBIL-SIDBI MSME Pulse, July 2026, 2026-07 . RBI Weekly Statistical Supplement, 23 October 2026, 2026-10-23 . Lok Sabha Starred Question 198, 2024-12-09 . Lok Sabha Unstarred Question 2466, 2026-08-03 . KPMG Impact Assessment of PMMY, NITI-sponsored, November 2023 .
Downloads
Sources and terms
- M3
- Broad money includes currency and bank deposits.
- CAGR
- Compound annual growth rate of nominal outstanding balances over March 2023 to March 2026.
- MUDRA PMMY Overall Performance, financial year 2024-25, Financial year 2024-25 .
- MUDRA PMMY Overall Performance, financial year 2025-26, Financial year 2025-26 .
- TransUnion CIBIL-SIDBI MSME Pulse, July 2026, 2026-07 .
- RBI Sectoral Deployment of Bank Credit, July 2026, 2026-08-31 .
- RBI Sectoral Deployment of Bank Credit, August 2026, 2026-09-30 .
- RBI Weekly Statistical Supplement, 23 October 2026, 2026-10-23 .
- Lok Sabha Starred Question 198, 2024-12-09 .
- Lok Sabha Unstarred Question 2466, 2026-08-03 .
- KPMG Impact Assessment of PMMY, NITI-sponsored, November 2023 .
- Economic Survey 2025-26, Box III.4, 2026 .